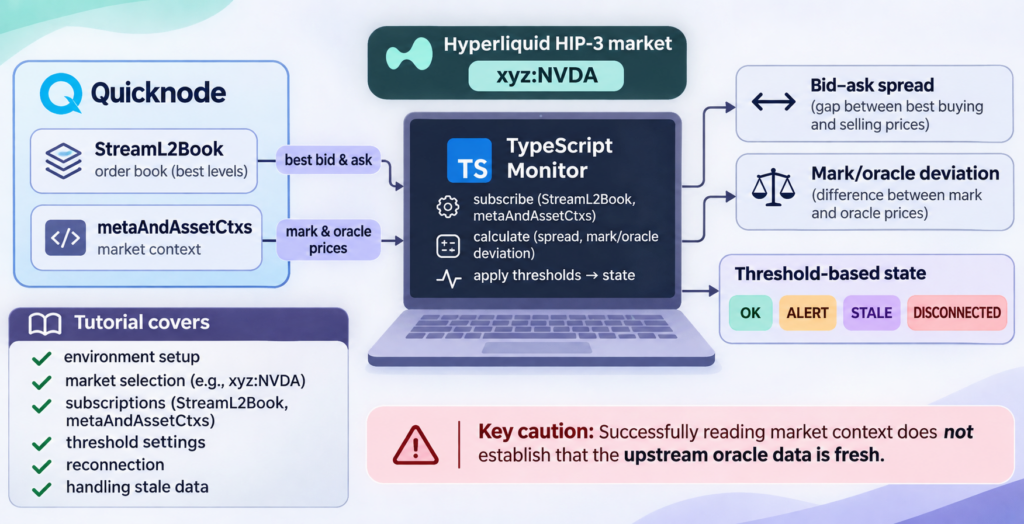
To monitor a Hyperliquid HIP-3 market such as xyz:NVDA, a builder needs both the best available bid and ask and the market’s mark and oracle prices. A tutorial published on November 18, 2026, describes a TypeScript monitoring process that obtains those values through Quicknode’s StreamL2Book and metaAndAssetCtxs interfaces.
The process calculates the bid–ask spread—the gap between the best buying and selling prices—and the deviation between the mark and oracle prices. It then reports threshold-based states including OK, ALERT, STALE and DISCONNECTED.
The tutorial covers environment setup, market selection, subscriptions, threshold settings, reconnection and handling stale data. Its key caution is that successfully reading market context does not establish that the upstream oracle data is fresh.